Go Solar Now.Roll It In Later.
Already closed, and the power bill is higher than you planned? QuiqBridge™ is temporary financing through participating licensed lenders that lets you own solar now, instead of leasing it. Later, if a refinance makes sense and you qualify, QuiqRefi™ may bring it into your mortgage.
Already closed? QuiqBridge™ is temporary financing that lets you own solar now. Later, if you qualify, QuiqRefi™ may bring it into your mortgage.
Free. A specialist checks your home with you. No credit check to start.
- You own the system
- No solar lease
- No dealer fee
- Option to refinance later
QuiqNest is not a lender or mortgage broker. Financing is provided by participating licensed lenders and is subject to credit approval and lender terms. QuiqBridge™ is temporary financing and is not Clear-Title Solar™. A future refinance is not guaranteed.
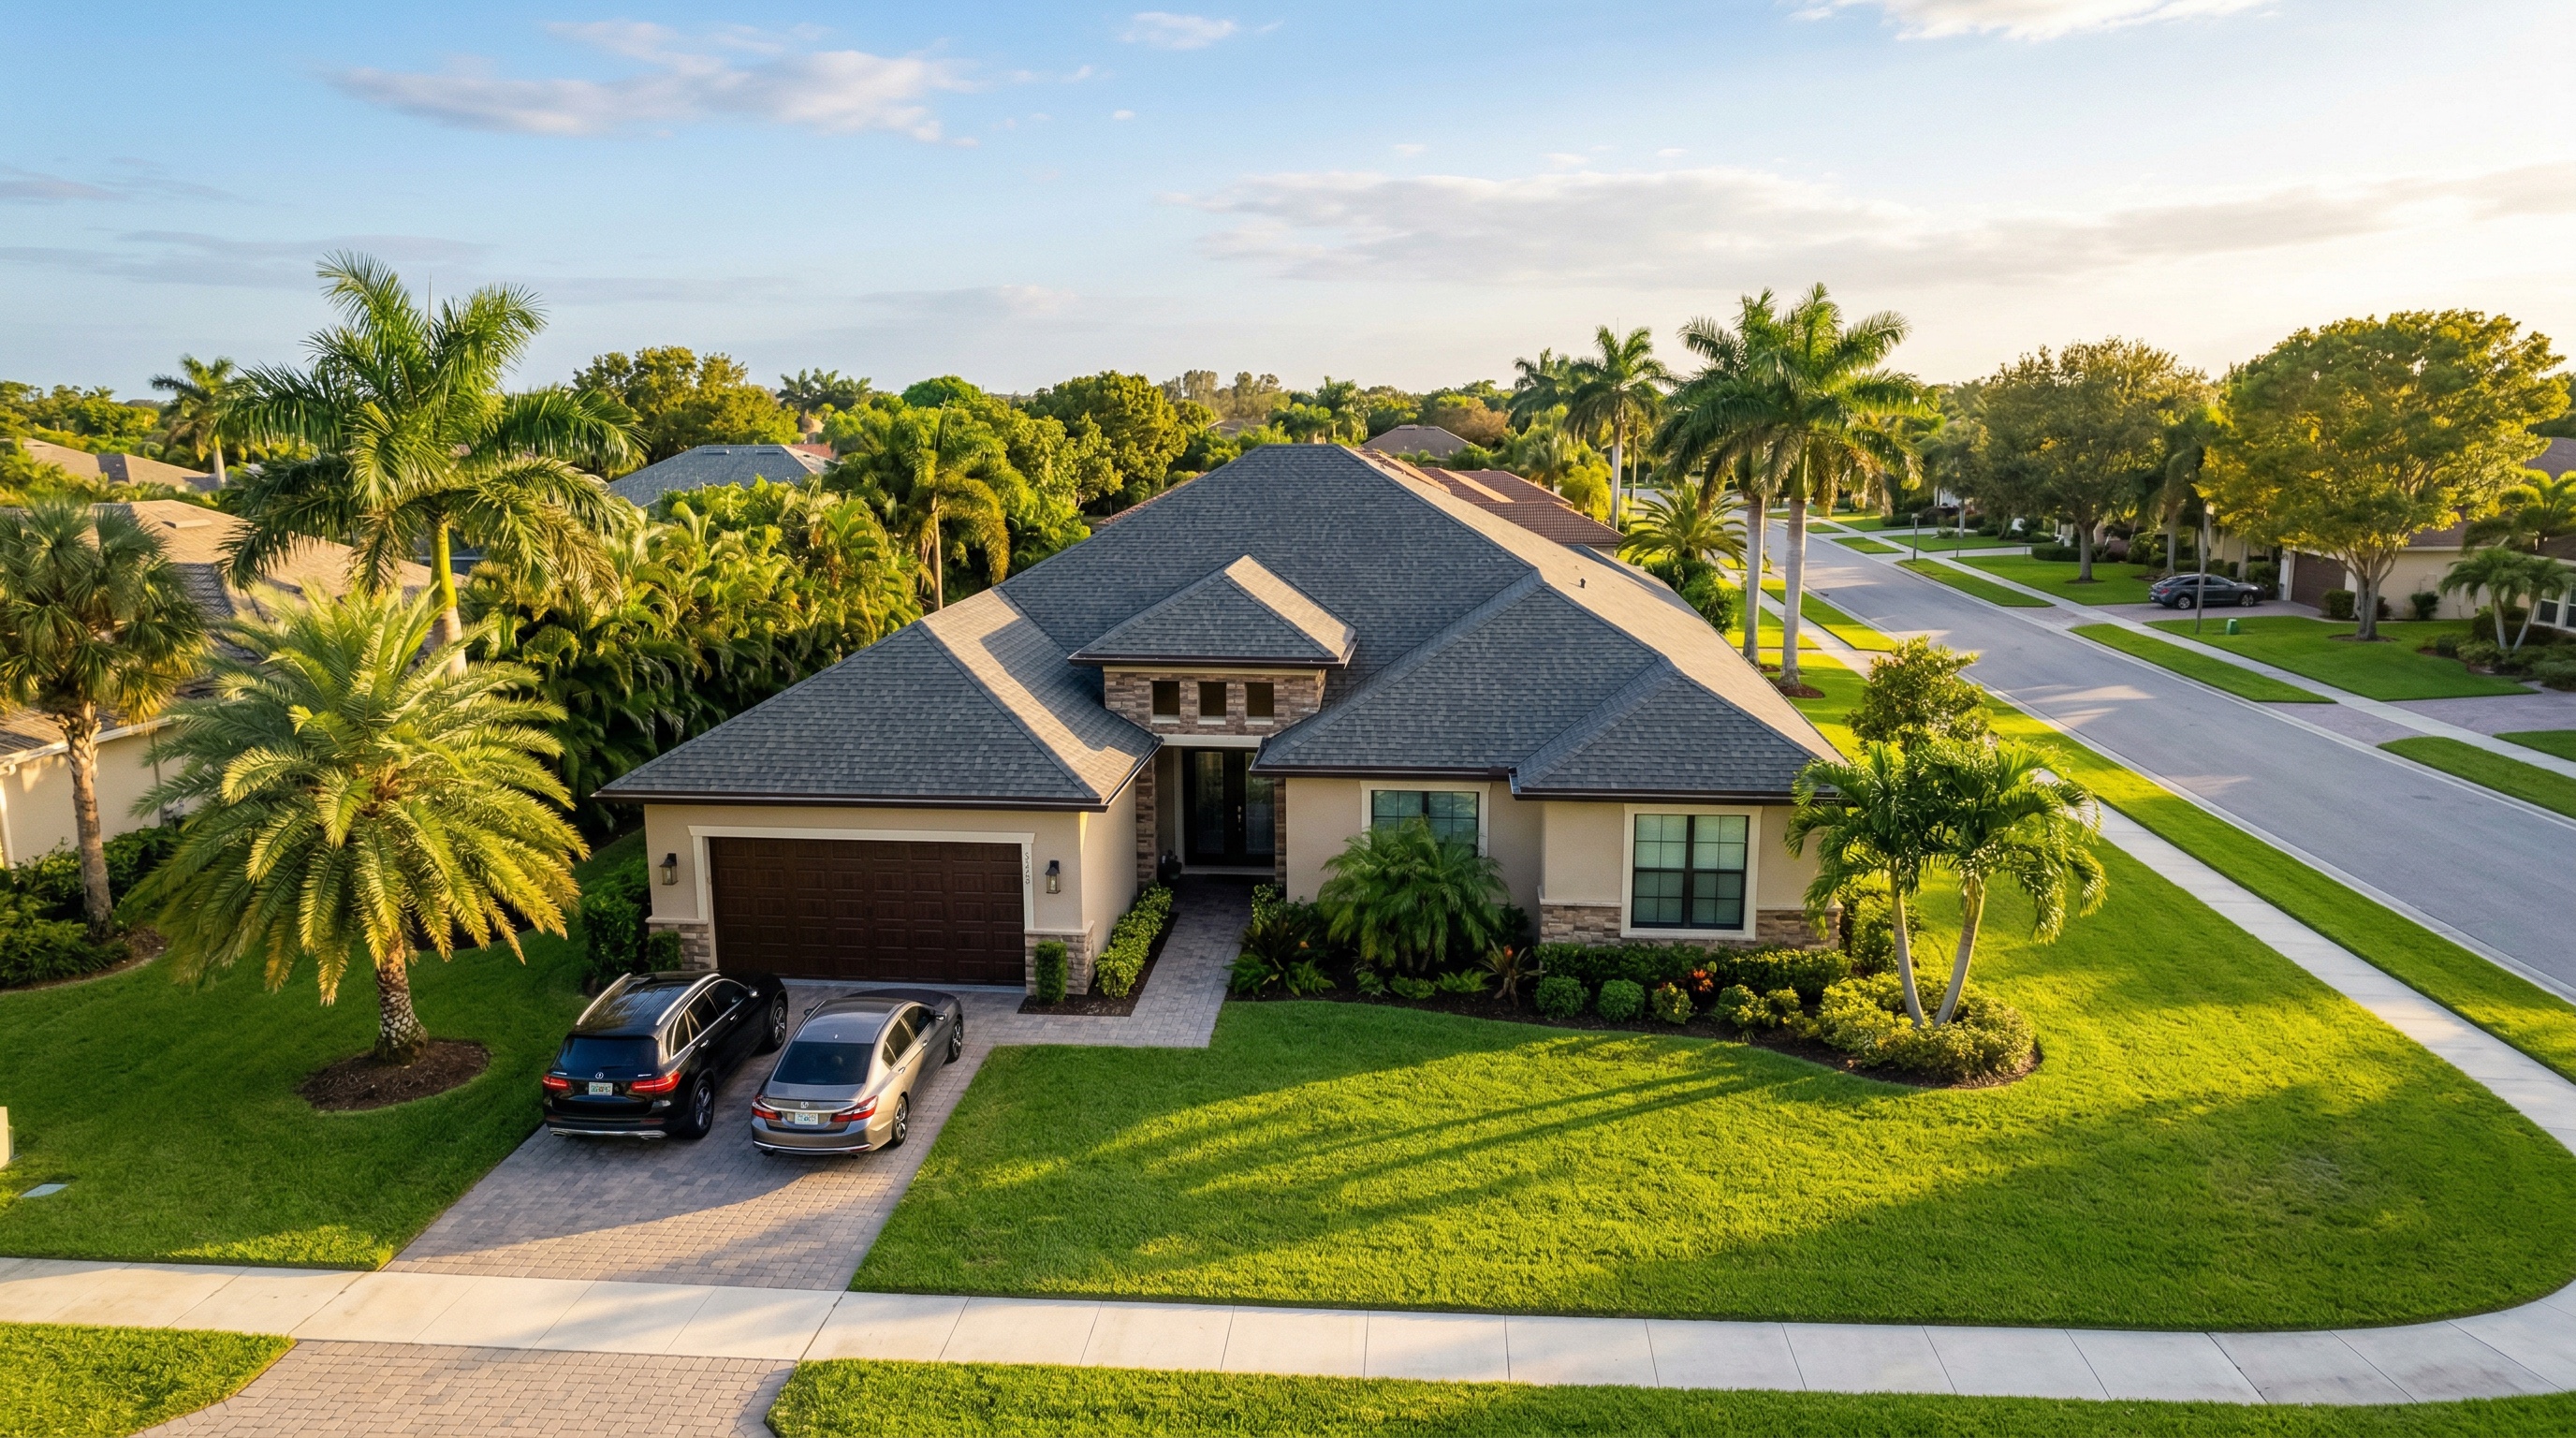
Not every home produces a Power Flip™. We show you the numbers first.
The power bill arrived. The equity did not.
Many homeowners start thinking about solar right after they move in, which is exactly when their financing options are thinnest.
The power bill shows up after you move in, and it is often higher than you planned for. It keeps coming every month, and you own nothing for it.
With a small down payment, there is not much equity for a HELOC. A cash-out refinance can mean giving up the rate you just locked in.
A solar salesperson offers to fill the gap, often with a lease or a dealer-fee loan signed at the kitchen table.
QuiqBridge™ gives you a better place to start: owned solar, financing you understand and the option to refinance it into your mortgage later.
Own the system. Know the terms. Plan the exit.
QuiqBridge™ is built for the gap between closing on your home and your next refinance, so you do not have to choose between waiting and leasing.
You own it
The system is yours. It is not leased, rented or owned by a solar company, and it is installed on the home you already own.
No dealer fee
QuiqBridge™ structures are built on financing without a dealer fee. Lender fees, closing costs and interest still apply, and they are disclosed before you sign.
Credit, not equity
FHA Title I home improvement loans are based on your credit and ability to repay, not your equity, so you do not have to wait years to start.
Built to be temporary
Later, QuiqRefi™ may pay off QuiqBridge™ and bring the solar into your mortgage. It is an option that needs lender approval, not an automatic conversion.
Approval, rates and terms are set by the lender. Not every homeowner or home qualifies.
Bridge it. Install it. Roll it in.
Temporary financing now. The option to refinance into your mortgage later, if you qualify.
- Step 1
Check your home
Send your address and a recent power bill. We check your roof, sun and numbers.
- Step 2
Review the structure
We show you how the financing works, including any filing, before you apply.
- Step 3
Apply with the lender
A participating licensed lender reviews your credit, income and debts.
- Step 4
Solar installed
Certified installer partners install your owned system.
- Step 5
Refinance later, if you choose
If a refinance makes sense and you qualify, QuiqRefi™ may pay off the bridge.
Timelines depend on the lender, your home and permitting.
Temporary financing, explained before you sign.
QuiqBridge™ is not Clear-Title Solar™. Depending on the size of your system and your situation, it uses one of these structures, and some include a UCC-1 filing.
Smaller FHA Title I loans, up to the program threshold, can be unsecured. They are not secured by your home or by the solar equipment.
Larger FHA Title I loans are secured by a mortgage or deed of trust that sits behind your first mortgage. That is a lien on the home, not a UCC-1 filing.
When a project is larger than Title I allows, or a lender's own solar loan is the better fit, the lender may record a UCC-1 fixture filing on the solar equipment until the loan is paid off.
Before you apply, we show you which structure fits your project and whether a UCC-1 filing is involved. You decide with the full picture.
Talk to a Specialist →The ROAD to Housing Act, signed in July 2026, raised the FHA Title I loan limits. Lenders are adopting the new limits as HUD issues guidance, so we confirm the current limit with the lender for your project.
QuiqBridge™ is not Clear-Title Solar™.
They solve different problems at different times. QuiqBridge™ is temporary financing after you close. Clear-Title Solar™ is solar financed inside your FHA purchase mortgage when you buy.
- For homeowners who already own their home
- Temporary financing, separate from your mortgage
- May include a lien on your home or a UCC-1 filing on the equipment
- May later be refinanced into your mortgage through QuiqRefi™, if you qualify
- For buyers purchasing a home with FHA financing
- Solar financed inside the FHA purchase mortgage
- No equipment-level UCC-1 fixture filing on the solar equipment
- Installed after closing, funded through an escrow holdback
Still shopping for a home? Plan solar into the purchase instead, with Clear-Title Solar™.
See Clear-Title Solar™ →What happens when you refinance or sell.
- It is a new refinance application, not an automatic conversion
- If approved, the new mortgage can pay off the QuiqBridge™ balance
- Once it is paid off, the bridge lender releases its lien or UCC-1 filing
- Any QuiqBridge™ balance is usually paid off at closing
- A loan secured by your home is paid off, or stays behind the new mortgage if that lender agrees
- A UCC-1 filing may need to be paid off, or released and filed again, as your loan contract allows
QuiqRefi™ depends on rates, your equity, the home and lender approval, and a refinance is never guaranteed. Payoff, release and recording fees can apply. Your loan documents set the exact terms.
Who is QuiqBridge™ for?
Homeowners who already closed and want owned solar now, especially when there is not enough equity yet for a HELOC or a refinance does not make sense today. Florida is our current focus.
Does QuiqBridge™ involve a UCC-1 filing?
It can. It depends on how your project is financed. FHA Title I loans do not use a UCC-1 filing: smaller ones can be unsecured, and larger ones are secured by your home. A lender's own solar loan, often used for larger systems, may include a UCC-1 fixture filing on the equipment. You will know which applies before you apply.
Is QuiqBridge™ the same as Clear-Title Solar™?
No. Clear-Title Solar™ is owned solar financed inside an FHA purchase mortgage, with no equipment-level UCC-1 fixture filing on the solar equipment. QuiqBridge™ is separate, temporary financing for homeowners who already closed, and some QuiqBridge™ structures do include a UCC-1 filing.
Do I need equity in my home?
Not for an FHA Title I loan, which is based on your credit and ability to repay. Each lender sets its own credit, income and debt requirements.
How much can I finance?
It depends on the structure, your credit and the lender. FHA Title I loans have maximums set by law and HUD. The ROAD to Housing Act, signed in July 2026, raised those maximums, and lenders are adopting them as HUD issues guidance. We confirm the current limit with the lender for your project before you apply. Larger systems may use a lender's own solar loan, which may include a UCC-1 filing.
Can I roll it into my mortgage later?
Possibly. QuiqRefi™ is a separate refinance, not an automatic conversion. If a refinance makes sense and you are approved, the new mortgage can pay off QuiqBridge™ and include the solar. It depends on rates, your equity, the home, an appraisal where required and lender approval.
What happens if I sell my home?
Any QuiqBridge™ balance is usually paid off at closing, and the lender then releases its lien or filing. Your loan documents set the exact terms.
Is there a dealer fee?
QuiqBridge™ structures are built on financing without a dealer fee. Lender fees, closing costs and interest still apply, and they are disclosed before you sign.
Will this affect my credit?
Checking your home with QuiqNest does not involve a credit check. When you apply, the lender reviews your credit, which may include a hard inquiry.
Is QuiqNest a lender?
No. QuiqNest is not a lender or mortgage broker. Financing is provided by participating licensed lenders. QuiqNest checks your home, prepares the solar side and coordinates the installation.
Is the interest tax-deductible?
Potential tax treatment depends on the borrower. Ask a tax professional about your situation.

Go Solar Now. Roll It In Later.
Send us your address and a recent power bill. A QuiqNest specialist checks your roof, sun and numbers, then walks you through which QuiqBridge™ structure could fit, including whether a UCC-1 filing is involved. No credit check to start.
Email Your AddressOr call (888) 733-0127Prefer to talk it through with a person?
Call or email the QuiqNest team about a specific home, FHA eligibility or your next steps.