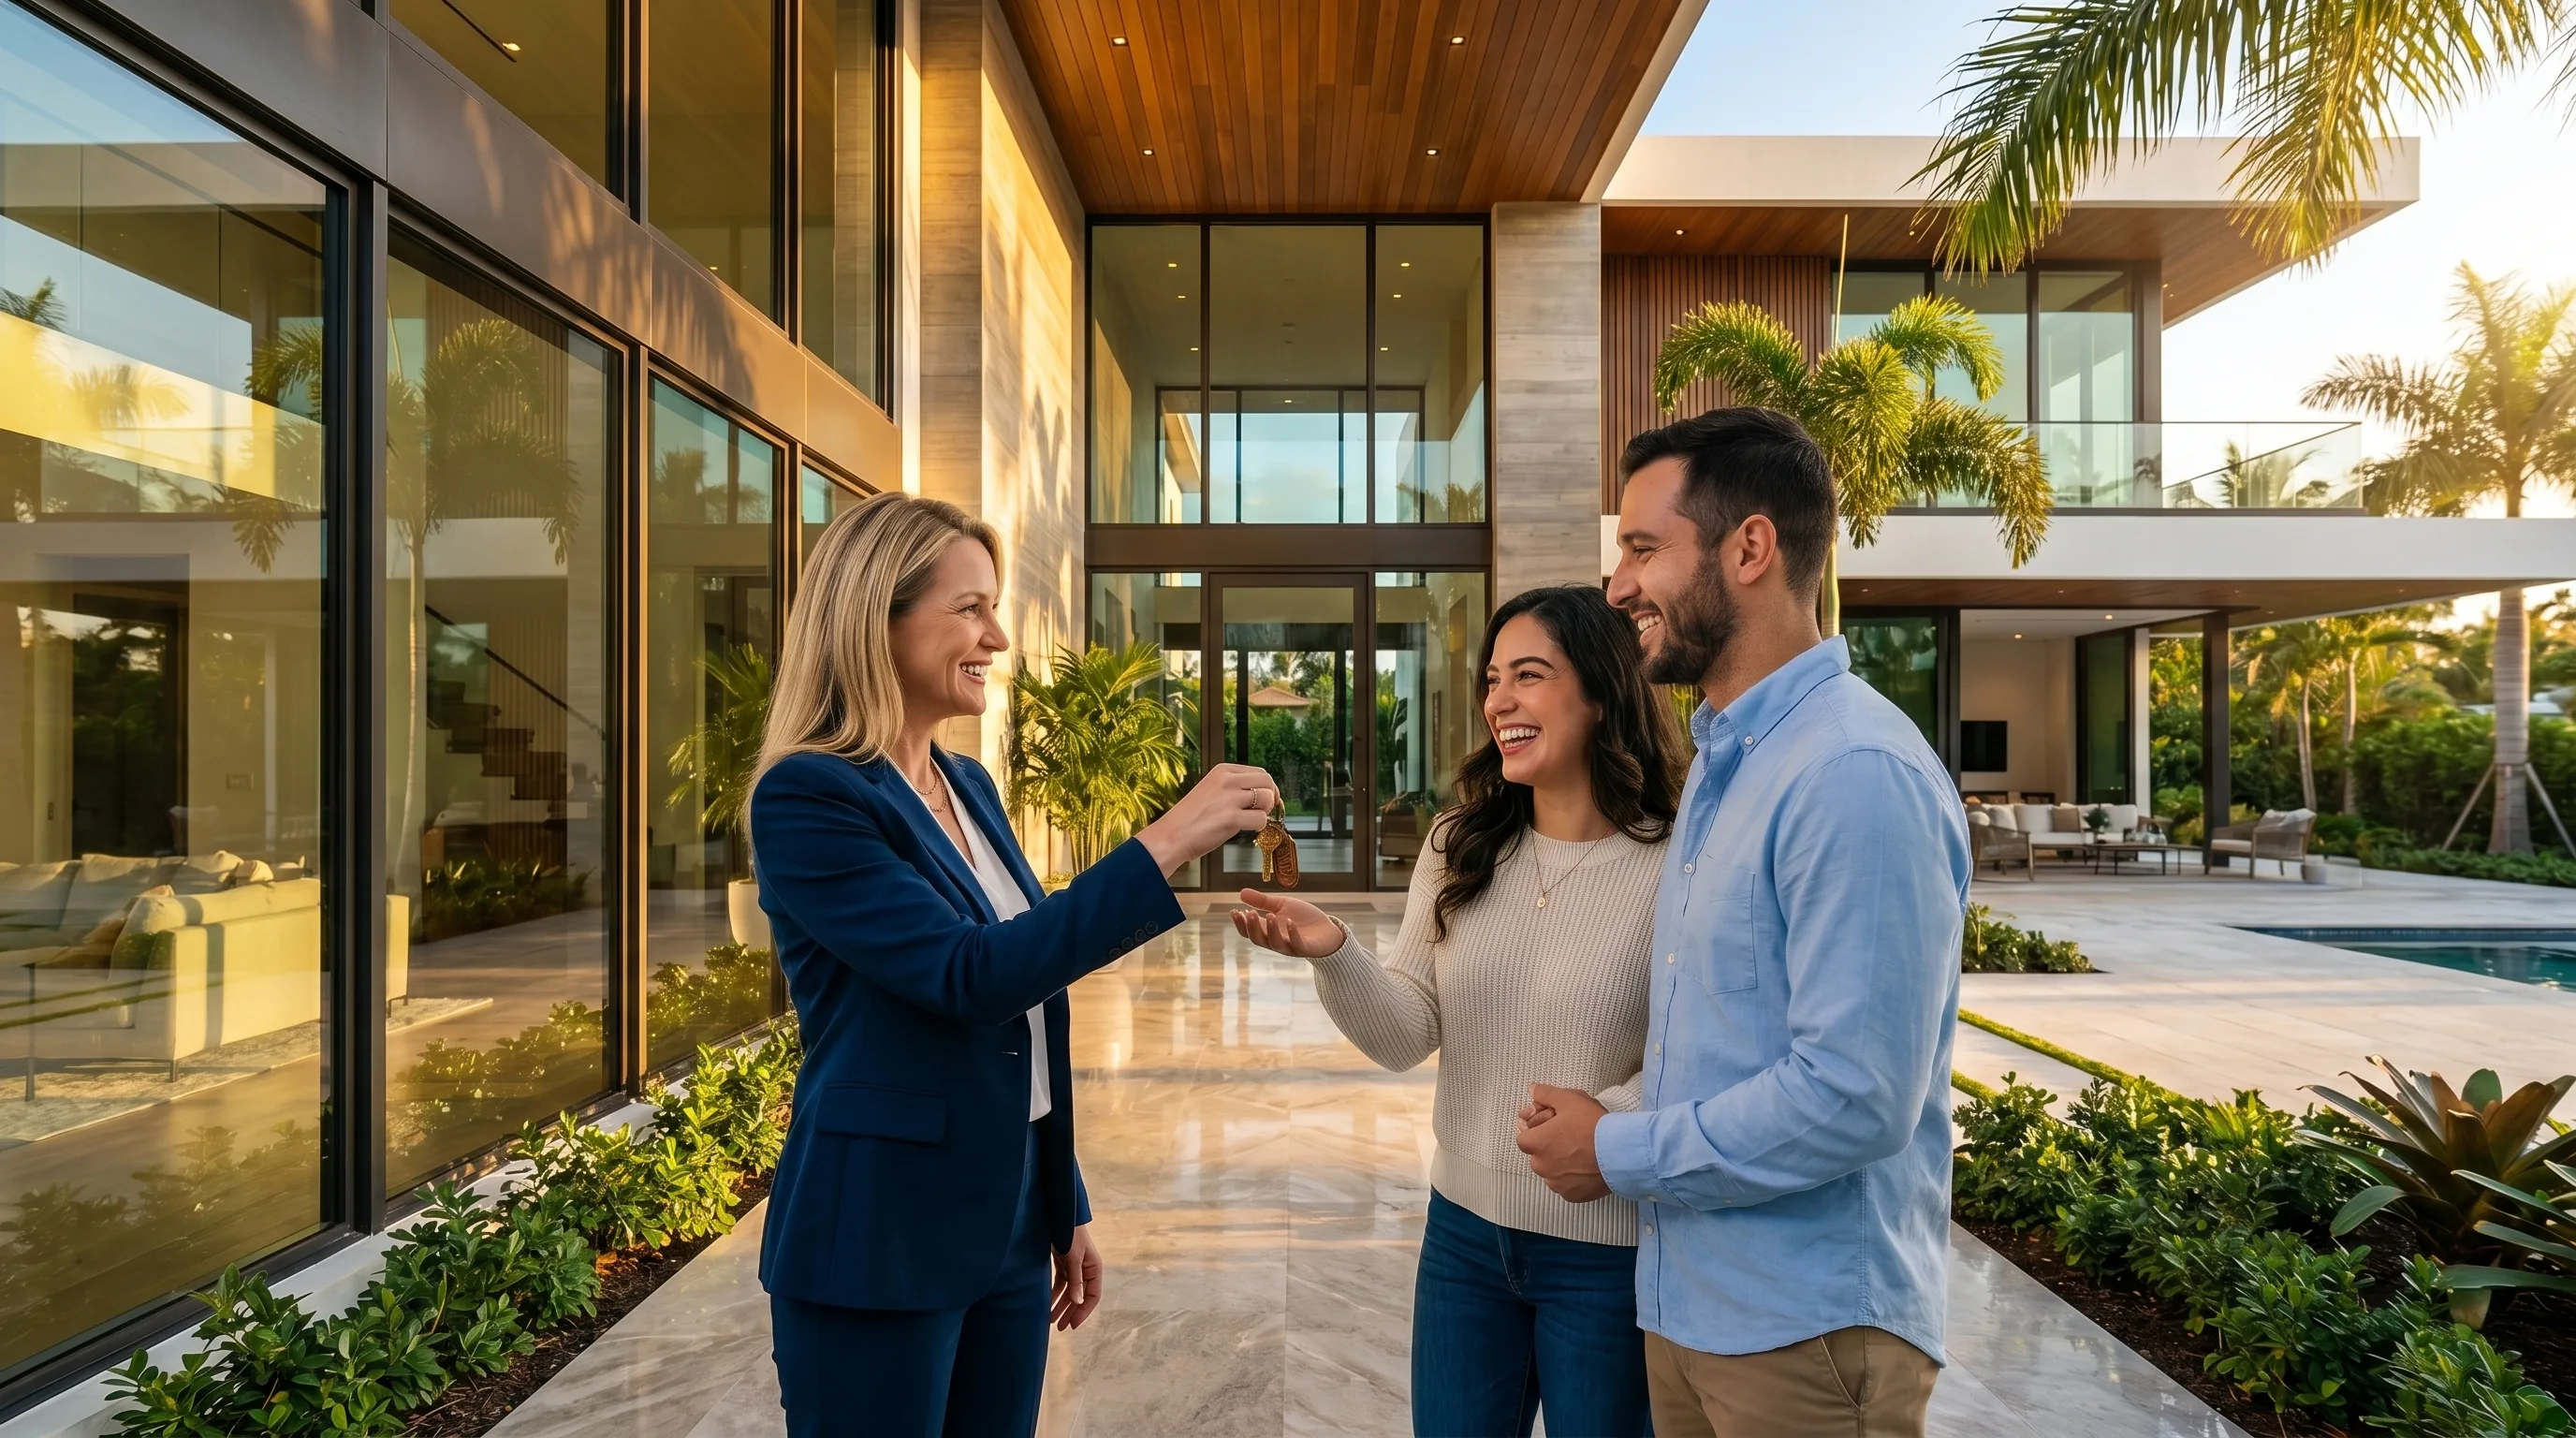
Same Down Payment.More Home.
Some Florida homes can include owned solar inside the same FHA mortgage. For the right home, money you would have sent to the power company goes toward something you own instead. Check any home before you tour it.
Some Florida homes can include owned solar inside the same FHA mortgage. Check a home before you tour to see what it really costs each month.
Free. Homes already in our database show results right away. New addresses get a full analysis in your free QuiqNest dashboard.
Prefer to talk first? Talk to a Specialist
- Same FHA cash down
- One mortgage, one payment
- Owned, not leased
- The home closes first
Subject to FHA program rules, borrower and property eligibility, and lender approval.
Calculated for that specific home. Projections, not guarantees. Not every home produces a Power Flip™.
Two homes. Same price. Different monthly reality.
The listing shows you the mortgage. It never shows you the power bill, and in Florida that second payment can change what a home really costs every month.
QuiqNest puts both numbers side by side before you fall for a house, so you tour the homes that actually work for your budget.
Illustration only. Every home's numbers are its own.
Put part of your power bill toward solar you own.
Every home has a power bill. With the Power Flip™, part of that spending may go toward an owned solar system, financed inside the same FHA mortgage. Whether your total monthly cost comes down depends on the home's roof, sun exposure and numbers, which is why we check each home first.
Today, it all goes to the power company
You pay for electricity every month, and none of that spending builds anything you own.
Owned solar joins the same loan
The eligible solar cost is added to your FHA mortgage. One loan, one payment, and the system belongs to you.
Part of the spend becomes yours
Part of what went to the power company now pays for a system you own. Where the home's numbers support it, your total monthly cost can come down too.
That shift is the Power Flip™, and Pre-Purchase Solar Integration™ makes it possible: the solar decision is made with the home decision, before you tour, and the system is installed after closing. Not every home produces a Power Flip™.
Check a Home →Three numbers for the home you are considering.
Every result is calculated for that specific home. No averages borrowed from someone else's house.
- 1Paste a Zillow link or street address for a Florida home.
- 2If the home is already in our database, its report is ready right away. If not, we run a full analysis.
- 3Add your email and your free QuiqNest dashboard keeps every home you check.
- 4When you are ready, a specialist walks you through next steps. Your lender confirms final eligibility.
Your closing stays on schedule.
The home closes first. Solar comes after, so it never holds up your purchase.
- Step 1
Check before you tour
See the home's real monthly cost before you book a showing.
- Step 2
Offer with the numbers in hand
You and your agent know what the home costs to own, not only what it costs to buy.
- Step 3
Close with one FHA mortgage
Eligible solar is financed in the same loan, with the same cash down, subject to program rules and lender approval.
- Step 4
Installed after closing
Certified installer partners install your system after closing, generally within 120 days, funded through an escrow holdback.
Built on the FHA Solar and Wind Technologies rules, HUD Handbook 4000.1, Section II.A.8.m.
Make Solar an Asset, Not a Liability.
How solar is paid for decides who owns it, how many payments you make, and what happens when you sell or refinance.
| Compared | Owned solar inside your FHA mortgageClear-Title Solar™ | Solar lease or third-party-owned arrangement | Separate solar loan |
|---|---|---|---|
| Who owns the system | You do | The solar company | You do, while a separate lender is repaid |
| Monthly payments | One mortgage payment | Mortgage plus a lease payment | Mortgage plus a solar loan payment |
| Filing on the equipment | No equipment-level UCC-1 fixture filing | Often a UCC-1 fixture filing | Often a UCC-1 fixture filing |
| When you sell or refinance | No lease to transfer and no separate filing to release | The lease is transferred to the buyer or bought out | The loan is usually paid off first |
General comparison. Terms vary by contract and lender, and normal title and lender review still apply.
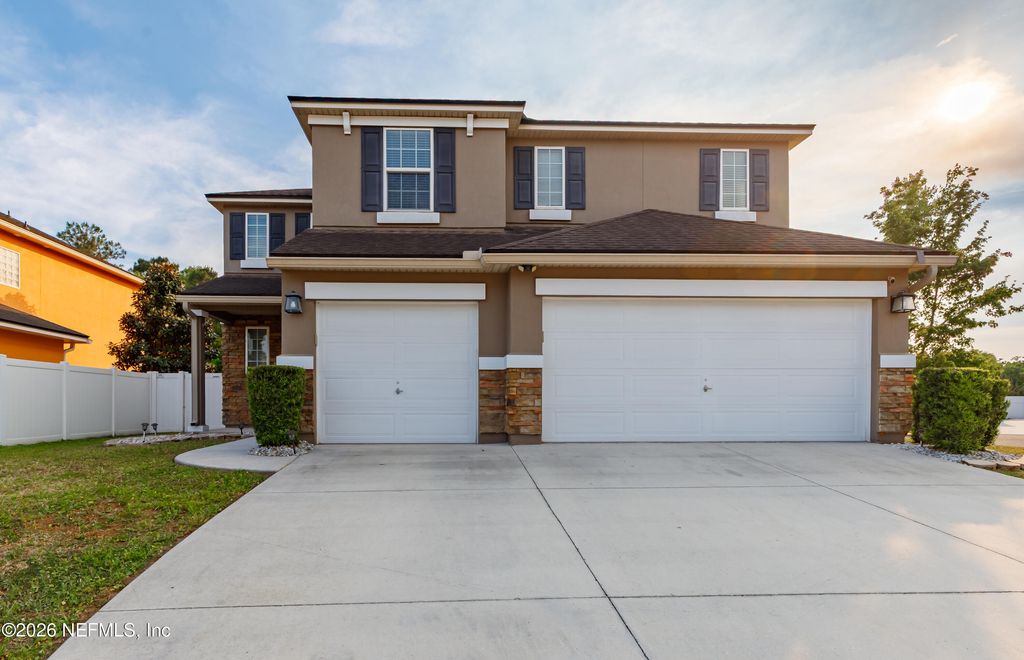
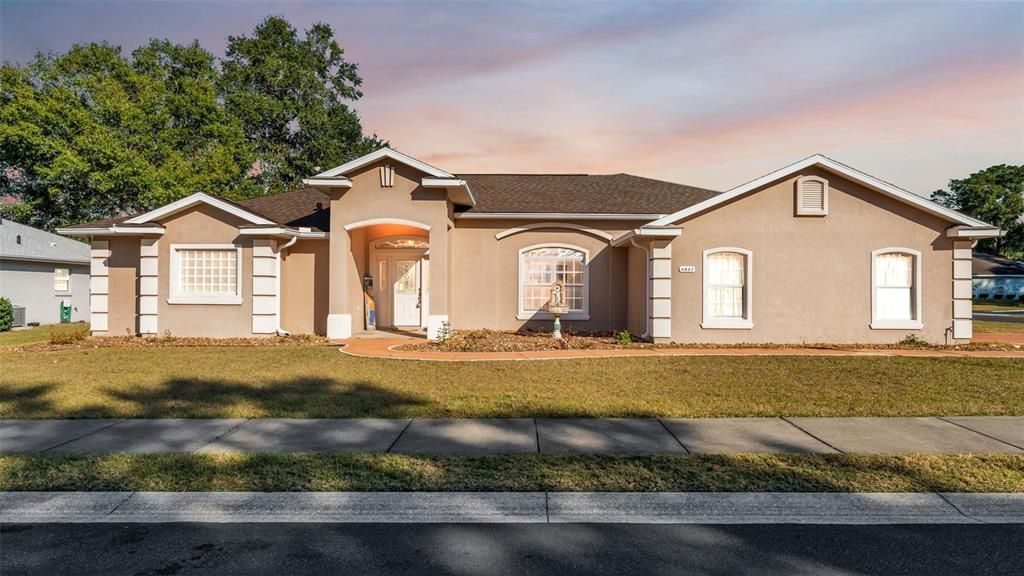
Start with homes we have already checked.
Solar-Ready Homes™ across Florida, each with its own Power Flip™ Analysis ready to view.

Already own a home, or help people buy one?

FHA already allows solar in your mortgage. We built the system that makes it work.
- A program that already exists. FHA Solar and Wind Technologies, HUD Handbook 4000.1. QuiqNest built the workflow that makes it practical for a home purchase.
- Licensed lenders handle every mortgage. QuiqNest is not a lender or mortgage broker.
- Certified installer partners. QuiqNest coordinates design, permits, installation and inspection after closing.
- Your data stays yours. We never sell it to solar dealers or third-party lenders.
Does adding solar change my down payment?
FHA calculates the minimum down payment on the home's value without the solar. The 3.5% is calculated on the home price, so financing eligible solar does not increase the cash you need at closing, subject to program rules.
Is solar installed before closing?
No. The home closes first. Your system is installed after closing, generally within 120 days, funded through an escrow holdback. Your closing timeline follows your lender's normal FHA process.
Does every home qualify?
No. The roof, sun exposure and the home's numbers all matter, and not every home produces a Power Flip™. Final eligibility for you and the home is confirmed by your lender.
Do I own the solar system?
Yes. It is owned, not leased, and financed inside your FHA mortgage. There is no separate solar loan and no equipment-level UCC-1 fixture filing on the solar equipment.
Does solar help me qualify for the loan?
You qualify on the full combined payment, as with any FHA loan. Your lender reviews your income, credit and the home.
Is QuiqNest a lender?
No. Mortgages are provided by participating licensed lenders. QuiqNest checks the home, prepares the solar side and coordinates the work after closing.
Is the interest tax-deductible?
Potential tax treatment depends on the borrower. Ask a tax professional about your situation.

Know Before You Tour.
Paste the home you are considering and see its numbers before you fall for it.
Prefer to talk it through with a person?
Call or email the QuiqNest team about a specific home, FHA eligibility or your next steps.