
Clear-Title Solar™for lenders.
Solar leases and separate solar loans can create refinance friction, title review and servicing-retention risk. FHA Solar and Wind Technologies (SWT) allows eligible solar to be financed inside the FHA mortgage.
FHA SWT allows eligible solar to be financed inside the FHA mortgage.
For mortgage lenders and loan officers.
- Inside the FHA mortgage
- No separate solar loan
- Borrower-owned system
- Installed after closing
QuiqNest is not a lender or mortgage broker. Financing is subject to FHA program rules, HUD guidance, borrower and property eligibility, and each lender’s own approval and overlays.
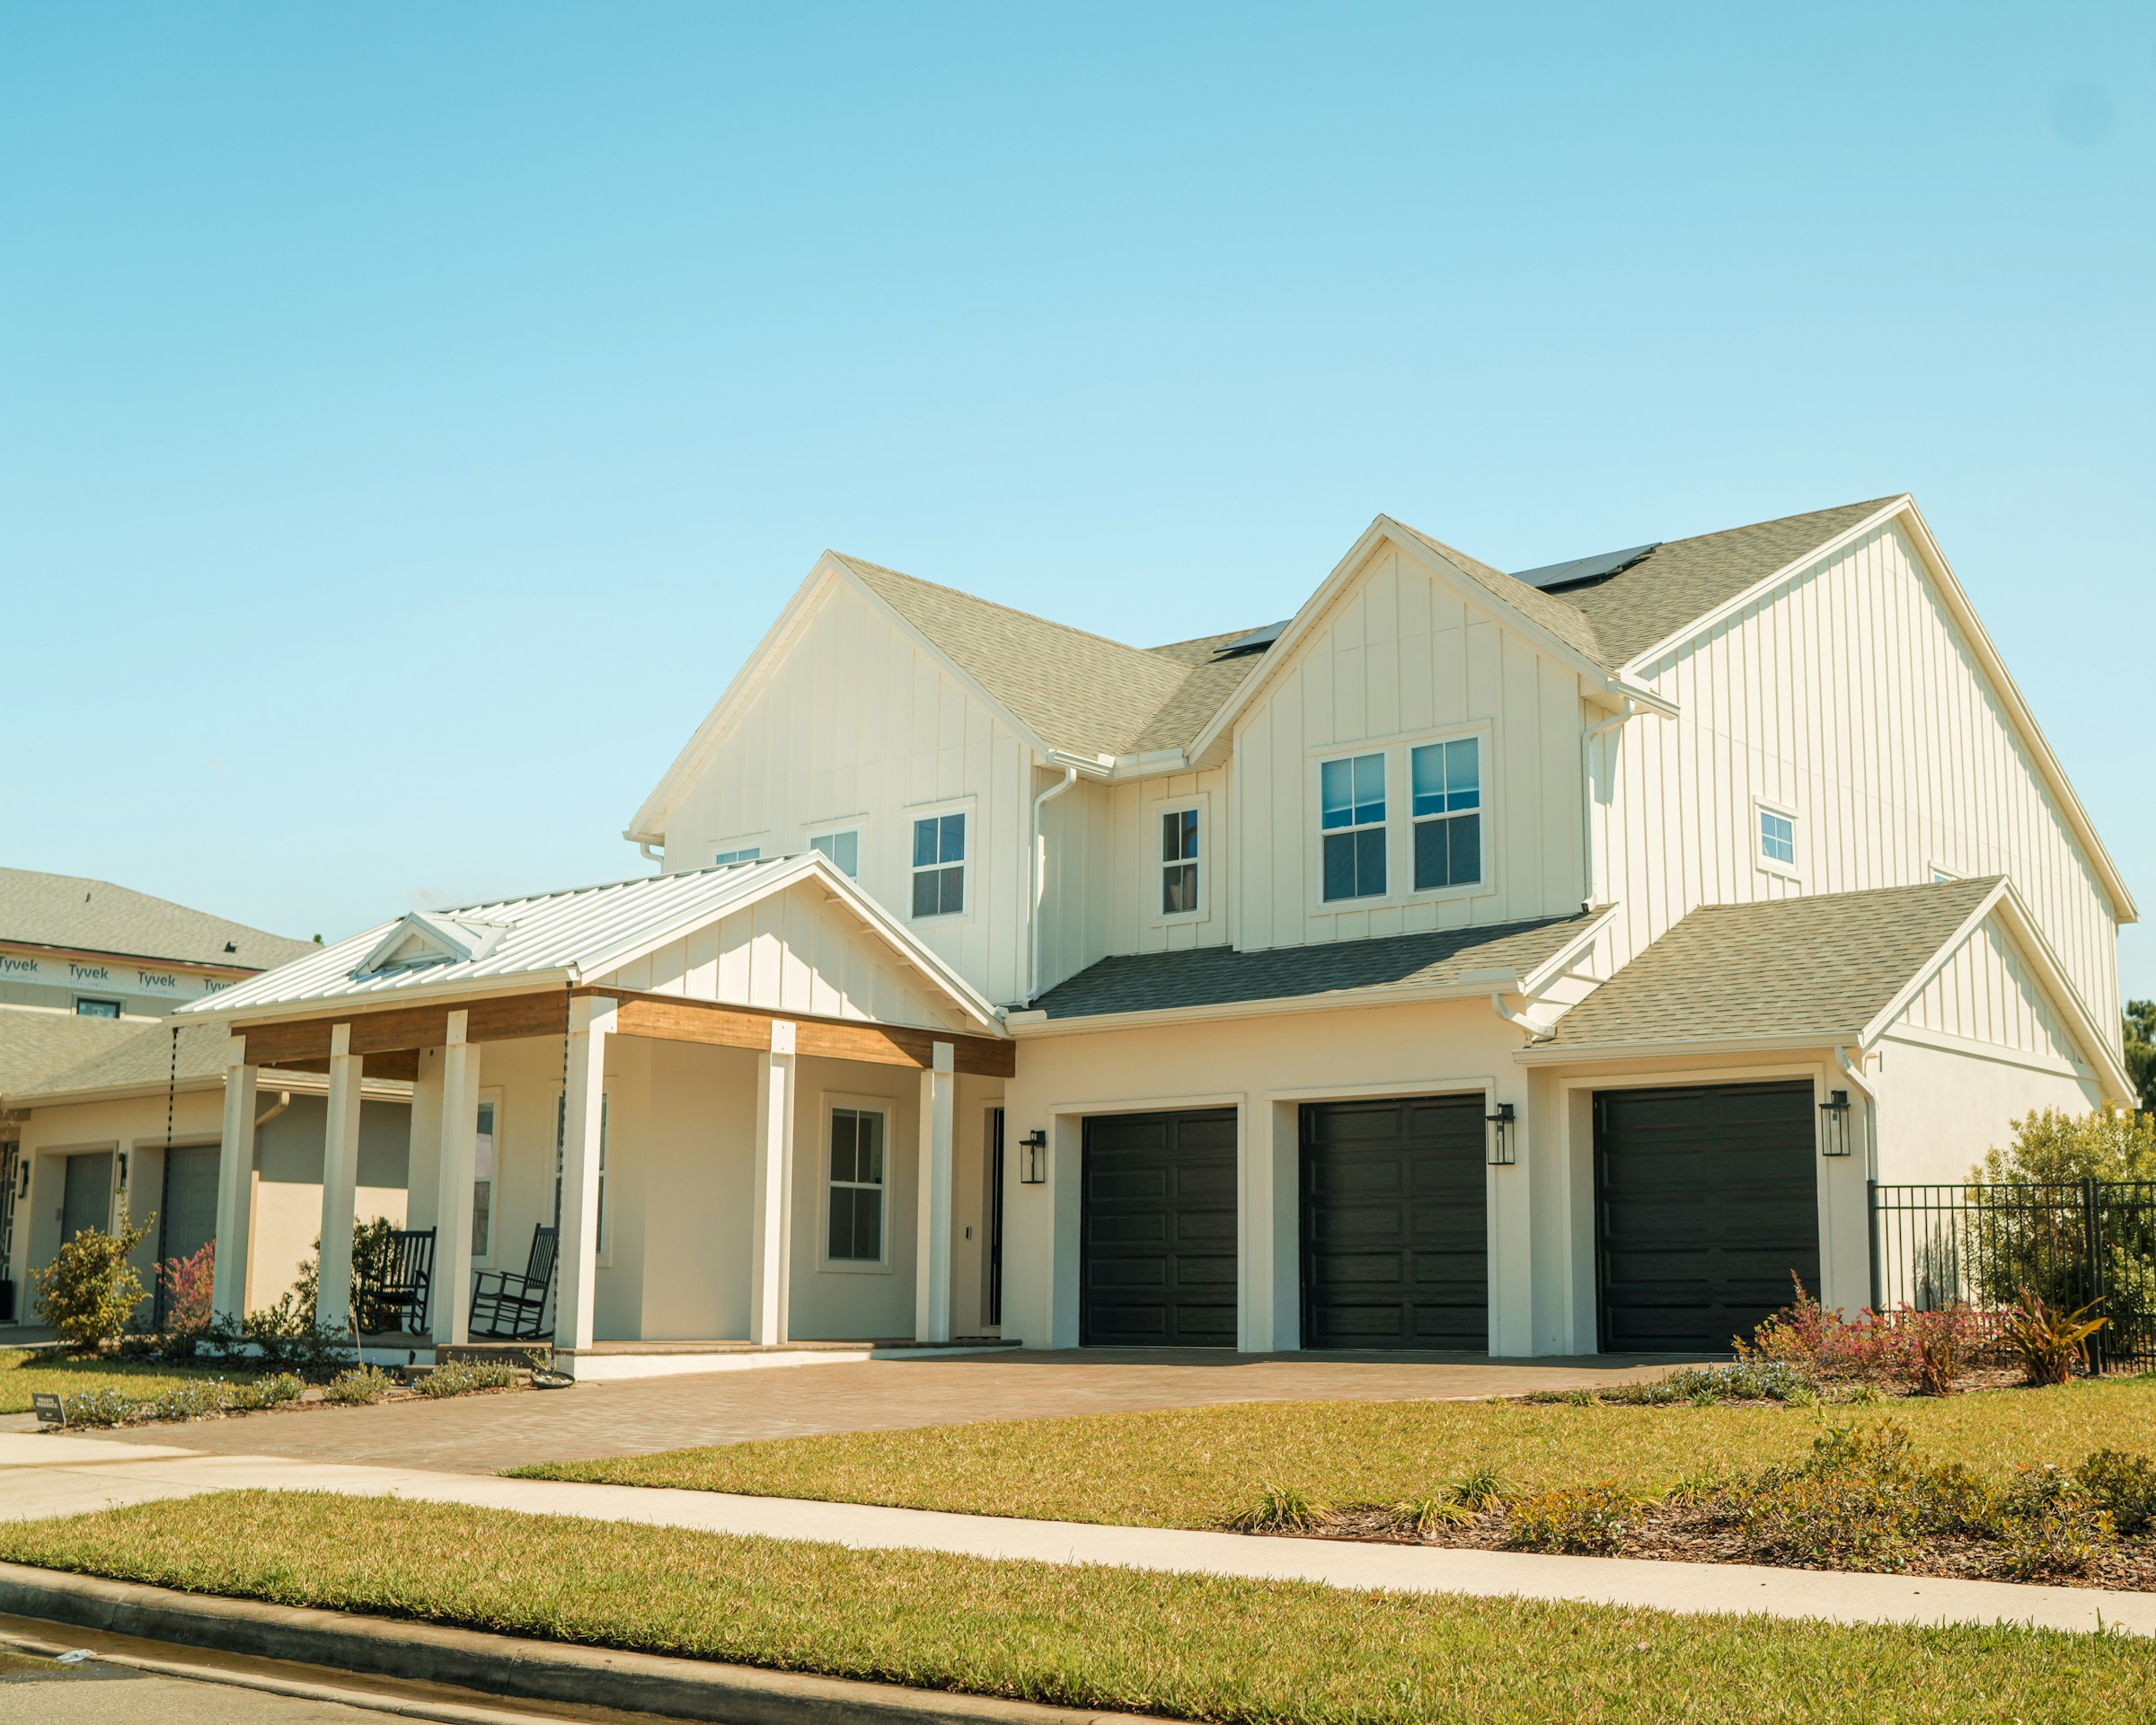
Defined in HUD 4000.1.
The FHA SWT program is an existing HUD structure that allows solar and wind systems to be financed inside a standard FHA mortgage. Confirm current parameters against HUD 4000.1 Section II.A.8.m.
Program
Defined in HUD 4000.1 Section II.A.8.m.
Purchase and rate-term refinance.
Borrower-owned system, no leases.
Structure
3.5% down payment calculated on home value only.
Solar value added up to 20% of appraised home value.
Eligible solar is financed as an addition to the FHA Base Loan Amount, subject to FHA program limits and lender approval.
After closing
Installation completed after closing, within 120 days.
Escrow holdback manages installer disbursement.
Standard FHA underwriting guidelines apply.
Solar outside the mortgage follows the loan.
When a borrower finances solar outside the mortgage, each structure adds friction at the moment retention matters most.
Refinance friction
A solar lease must be subordinated or assumed, which can slow or block a refinance.
Debt-to-income
A separate solar loan adds a monthly obligation that affects debt-to-income and future underwriting.
Title review
UCC-1 filings from solar lenders can trigger objections and title-company delays. Subordination requests depend on solar companies with little incentive to move quickly.
Retention
Borrowers may refinance away to remove or work around solar debt, taking the servicing relationship with them.
One mortgage. One payment. One servicer.
FHA SWT places eligible solar inside the mortgage from the start, so there is no separate financing instrument to manage, subordinate or negotiate around.
- Solar is financed within the FHA mortgage
- No separate solar loan at closing or after
- The borrower owns the system
- No equipment-level UCC-1 fixture filing
- No third-party solar company holds a competing obligation
- One monthly payment
- One servicer relationship
- The refinance path stays open
Each loan remains subject to FHA program rules, HUD guidance and the lender’s own approval.
Fewer reasons to refinance away.
MSR value depends on retention. The FHA SWT structure is designed to reduce the solar-related triggers that lead borrowers to refinance elsewhere.
No competing solar filing
The system is part of the FHA loan. No equipment-level UCC-1, no subordination and no third-party solar servicer on refinance.
No third-party solar payment
Solar is inside the mortgage, so the borrower has no separate monthly solar payment.
Servicing relationship preserved
Rate-term and cash-out refinance opportunities can stay within your portfolio.
Less refinance leakage
Borrowers have no solar-financing reason to refinance away.
The workflow that makes FHA SWT usable.
QuiqNest is the workflow layer between lender origination and solar installation, so lenders plug into a coordinated process instead of managing solar tasks internally.
Borrower pre-qualification
Borrowers are screened for FHA SWT fit before the loan enters processing, reducing mid-pipeline surprises.
Solar readiness assessment
Property suitability is reviewed early: roof condition, orientation and electrical service, before appraisal.
Installer coordination
QuiqNest manages the borrower and licensed installer relationship, from proposal through installation after closing.
Appraisal and underwriting package
Structured appraisal instructions and the solar documentation, installer credentials and SWT materials are packaged for the file.
Escrow tracking
QuiqNest tracks escrow holdback disbursements and monitors the 120-day installation window.
Lender keeps the loan
The participating lender originates and services the FHA loan. QuiqNest coordinates the SWT workflow around it.
You originate. QuiqNest coordinates.
QuiqNest connects FHA borrowers, participating lenders and installation partners. Participating lenders originate the loan, and QuiqNest coordinates the SWT workflow around it.
- Originates the FHA loan through standard FHA origination
- Adds solar through the SWT program at underwriting
- Coordinates borrower qualification, installer sourcing, appraisal support and escrow
- Routes qualified FHA SWT borrowers to participating lenders in their market
- Installs after closing
- Coordinated by QuiqNest, keeping the lender clear of contractor management
QuiqNest does not approve loans or set rates. Each participating lender makes its own credit decisions.
Become a Participating FHA SWT Lender.
QuiqNest connects FHA borrowers, vetted installers and lenders in a single workflow.
Become a Participating FHA SWT LenderOr Talk to a SpecialistPrefer to talk it through with a person?
Call or email the QuiqNest team about a specific home, FHA eligibility or your next steps.
